Lines on the Map. Redlining and the Financial Architecture of America
Racial inequality in the United States is not accidental. It is designed. Redlining transformed racism into policy, embedding segregation into the financial and urban structure of American cities. Its consequences remain visible today.
There is a scene in Boyz n the Hood that should be shown at the start of every urban economics course. In it, Furious Style - the “wise man” of the movie, played by Lawrence Fishburne - gathers a group of kids from Compton and explains the real estate market in terms of a simple yet devastating mechanism of segregation. He talks about houses, prices, rates, “gentrification”, and invisible borders that determine who can live where. In other words, he explains that a neighbourhood is not just a place to live in. It is, first and foremost, a financial dispositif.
This scene is one of the most honest portrayals of American cities that Hollywood has ever produced. If you really want to understand why the United States is the way it is — expanses of suburbia and islands of downtown, roads that separate rather than connect — you have to start with houses. You have to consider the fact that living in America has been intimately connected with the country's financial infrastructure for decades.
As with many issues in contemporary US history, the roots of the problem can be traced back to the Great Depression. More specifically, to the plan implemented by Roosevelt in the mid-1930s to rescue the American economy, i.e. the New Deal. It was at this time that the importance of the real estate market in the credit cycle was recognised, and that housing was acknowledged as not only a private matter, but also a fundamental part of the asset structure of modern societies. As such, it requires standards, rules, and guarantees. Above all, it requires an entity — in this case, the state — to act as director and referee. This led to the creation of several institutions that would invisibly or visibly shape America in the decades to come, most notably the Home Owners' Loan Corporation (HOLC) and the Federal Housing Administration (FHA).
The contemporary real estate mortgage originated in 1930s America and was shaped by these two institutions, not on the basis of a romantic notion (the “dream of a house”), but of a bureaucratic and financial necessity: making credit manageable on a wide scale. Debt had to become a form of “economic citizenship”, not an exception or an aberration. For that to happen, a sustainable debt model had to be created, namely the real estate mortgage (equivalent to the Italian mutuo): longer duration, more affordable installments, “reduced” risk. It was the standardization of the future: an entire country learning to plan based on contracts.
However, the point is that every contract involves selection. If you are creating a “safe” market, you have to decide what is and what isn’t safe. The FHA and other federal agencies began to think in these terms: which areas are financeable, which neighborhoods guarantee that home values will grow at rates that offset interest rates and inflation, and which are at risk of “depreciation.” The language they use to express these considerations is cold and bureaucratic. But within that language, as is often the case in America, there is an implicit racial subtext which is not a bug in the system: it is one of its features.
For the risk, in this context, isn’t just an economic variable. It is a social judgment disguised as a technical criterion. For the FHA parameters, “risky” can mean “poor neighbourhood”, but also "unstable neighbourhood”. And, in many documents from that time, “unstable” meant one very specific thing: not white enough.
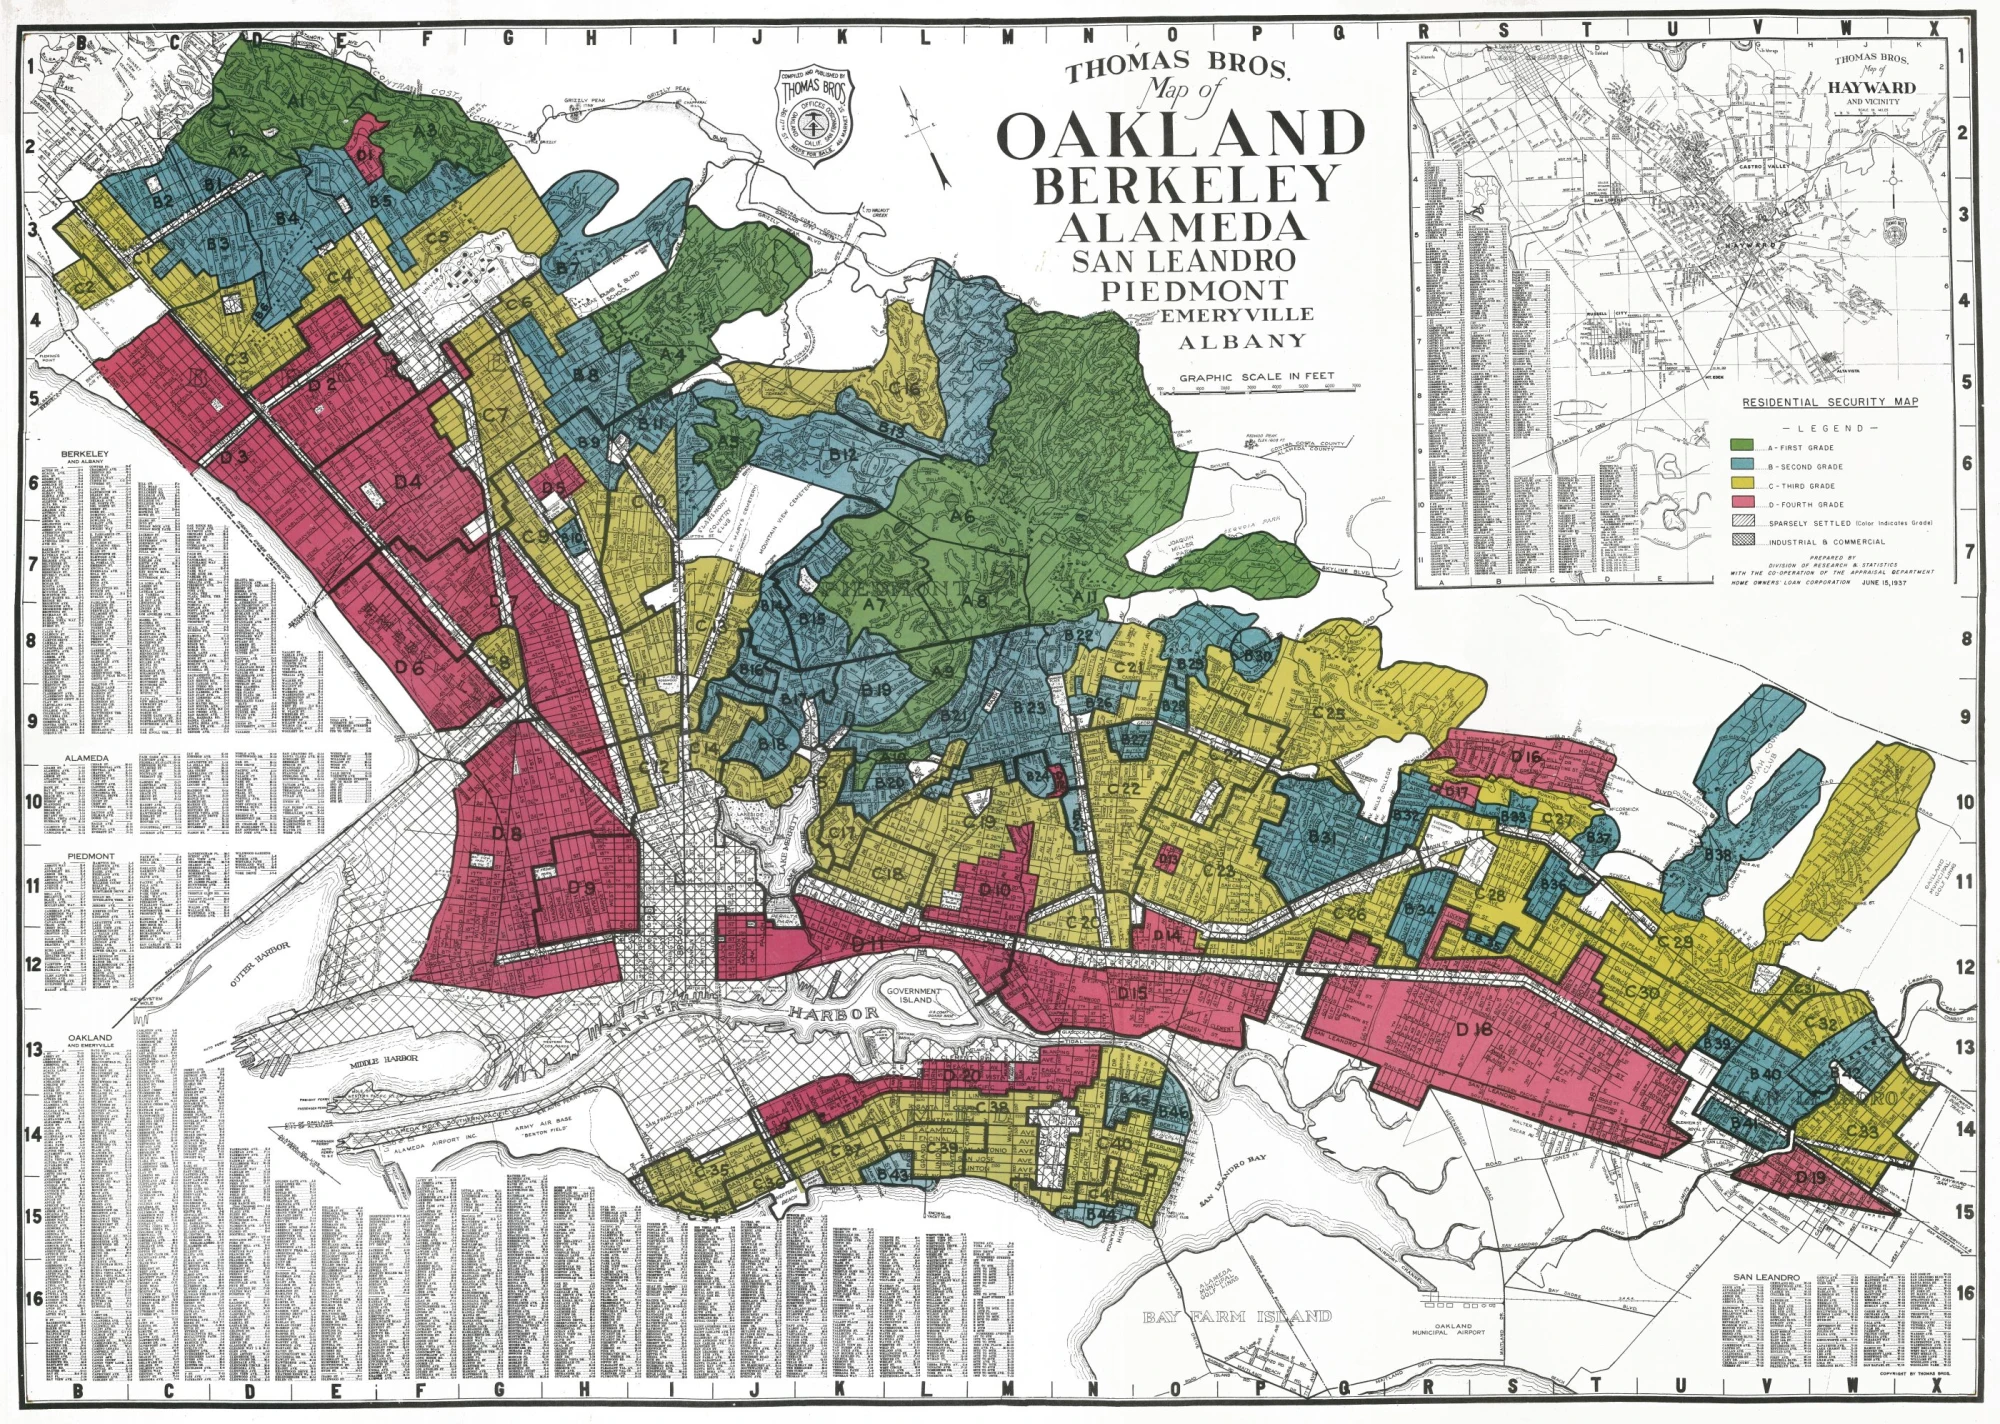
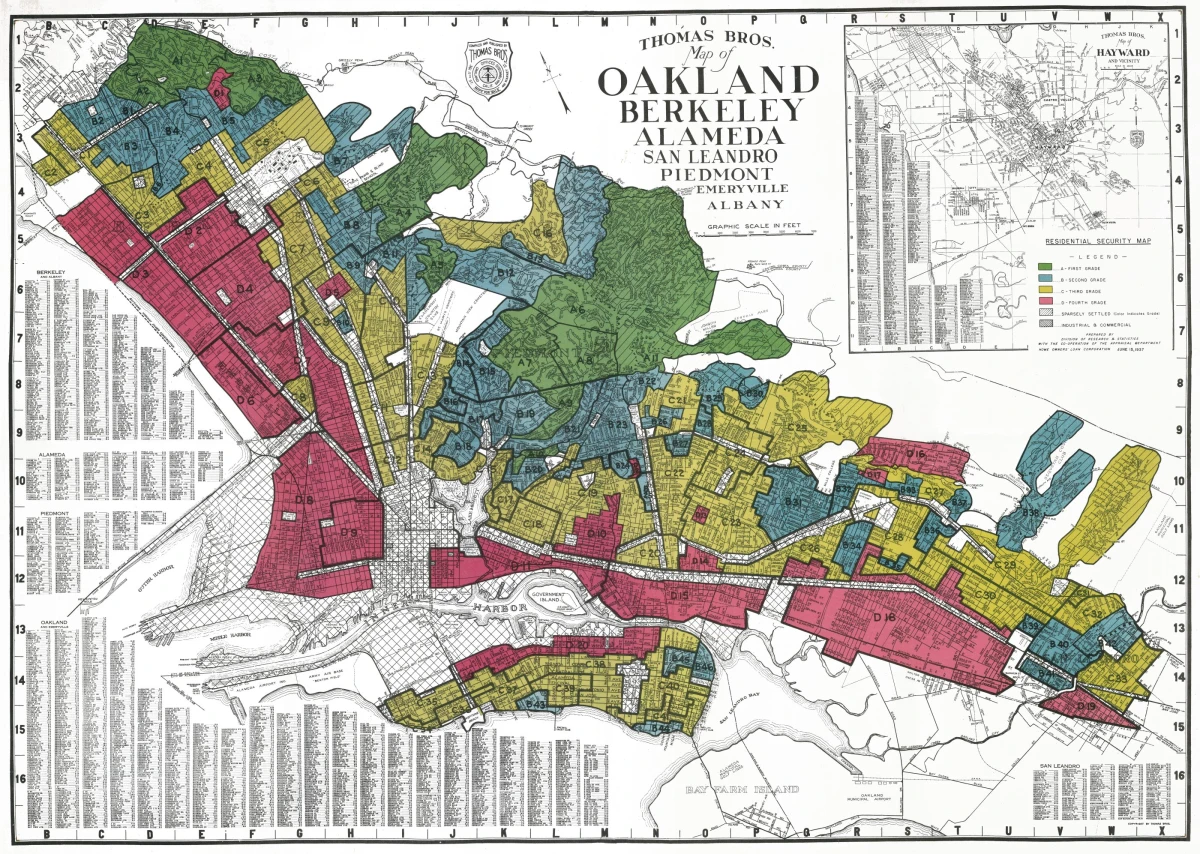
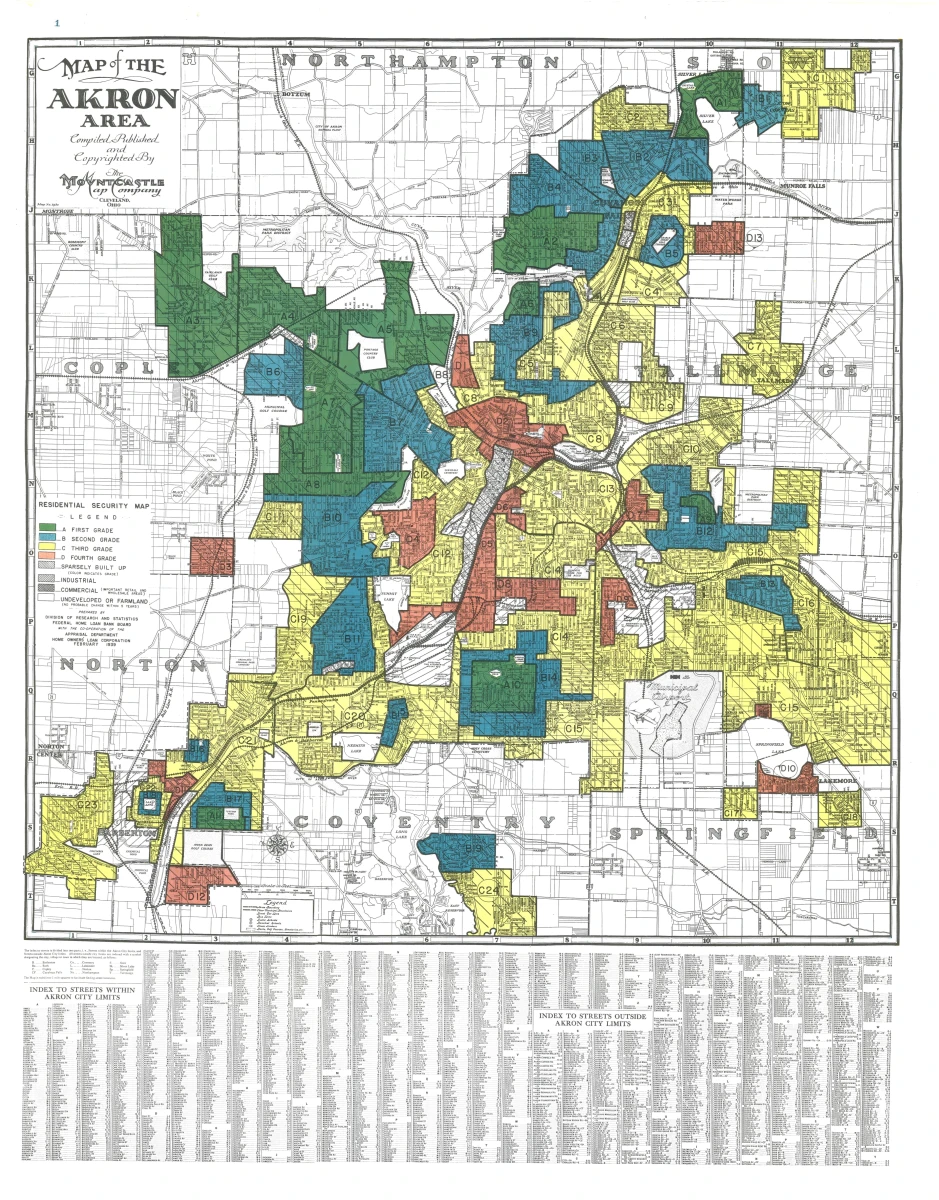
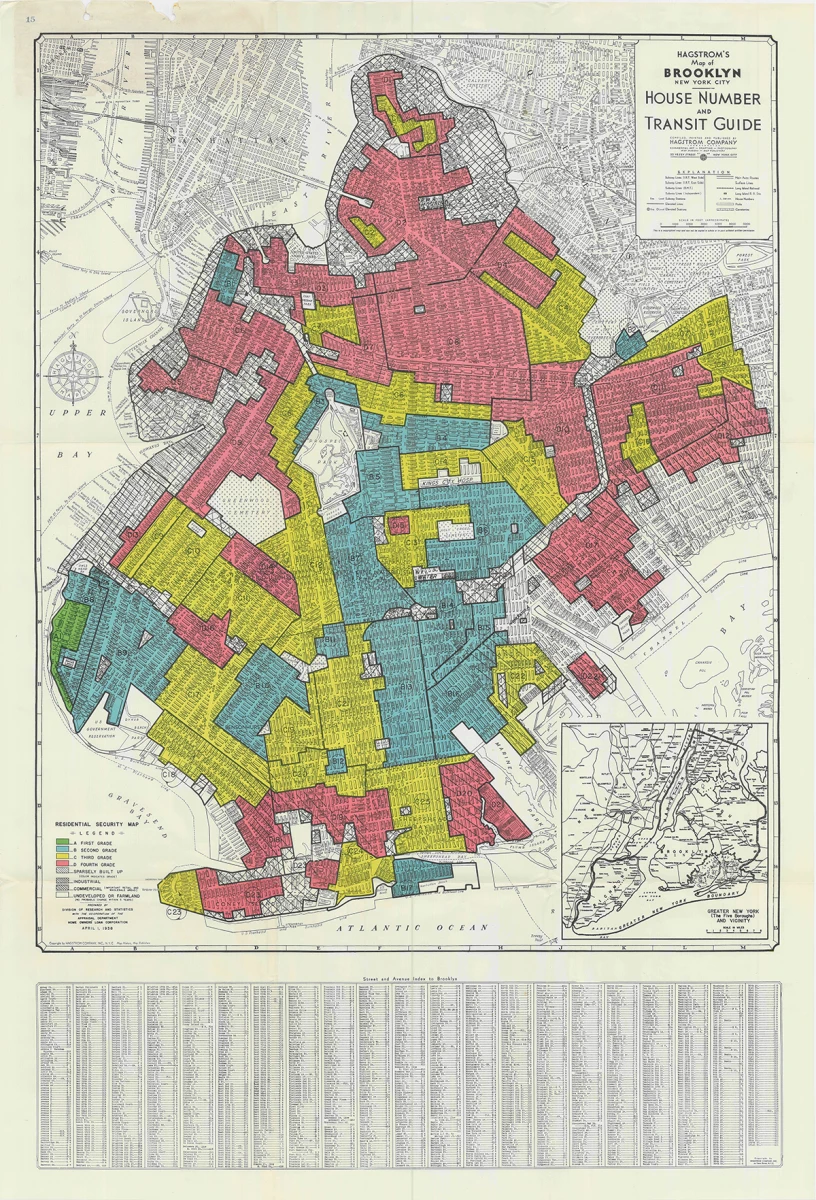
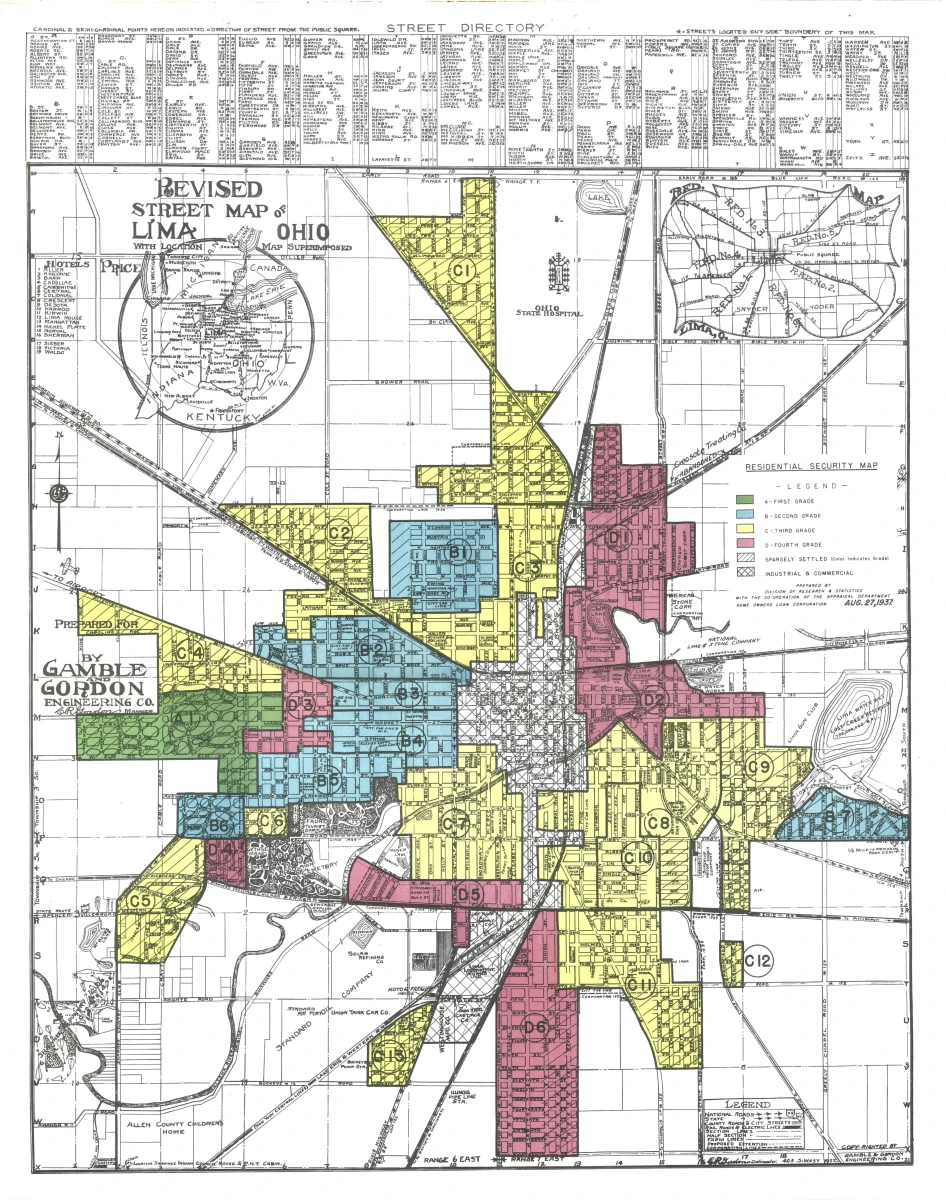
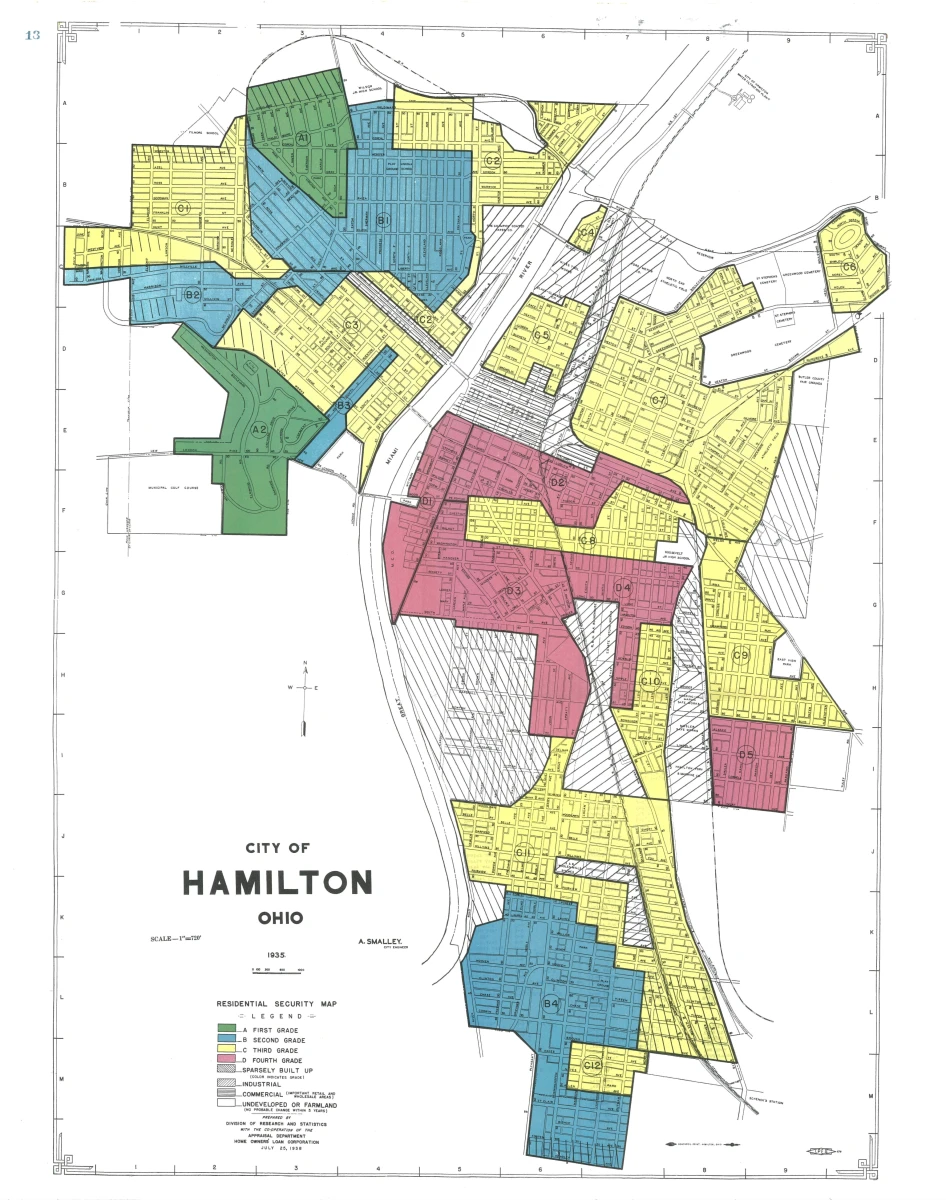
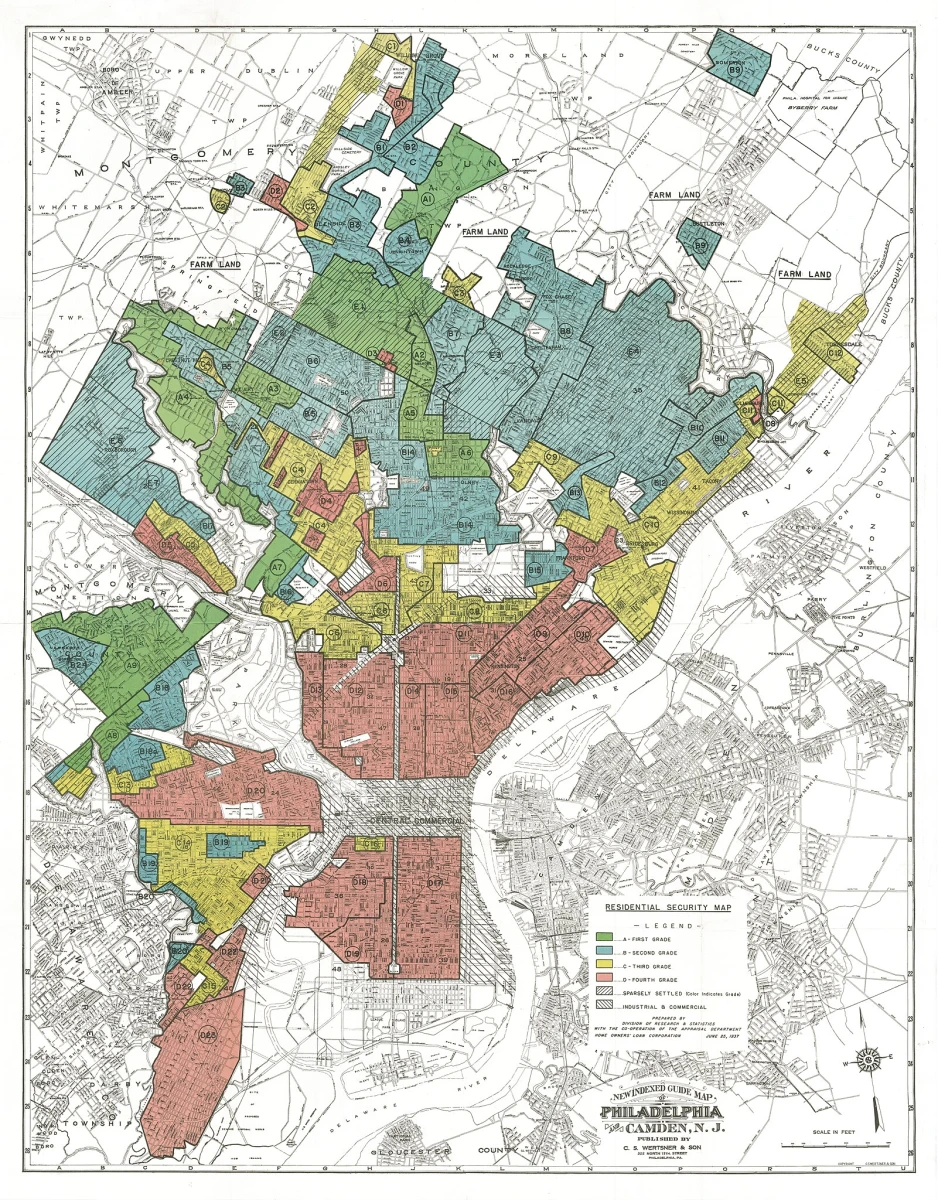
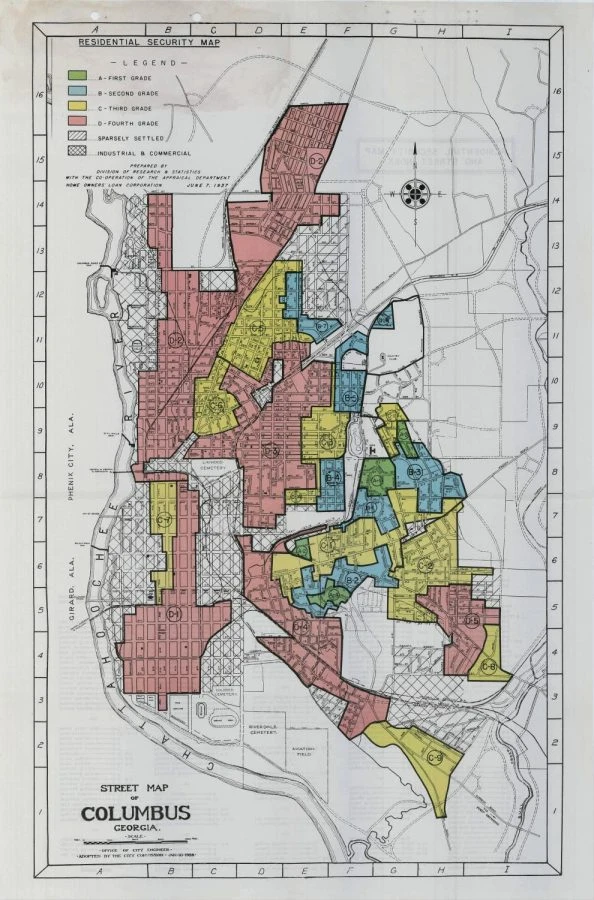
This is how we arrive at what would later be called redlining. In the 1930s, the HOLC began producing so-called Residential Security Maps: city maps in which neighbourhoods were classified according to their financial “reliability.” Green indicated the “best” areas, blue those that were still considered solid, yellow those “in decline”, and red those considered hazardous. Can you guess the racial composition of the hazardous areas?
From the outset, the modernization of American real estate has been accompanied by a Pynchionesque inherent vice: in order to govern the market, it must be made orderly; to do so, anything perceived as disorderly must be excluded. The house became the main tool through which the state built a middle…